— Mortgage Brokers Frenchs Forest
Home loan solutions, that are tailored to you.
WE COMPARE 60+ BANKS & LENDERS INCLUDING
— A simple process You'll love
More options are available, even if you're months away from buying or refinancing.
Many of our Frenchs Forest clients aren't ready to buy, they're planning, researching & weighing up options.
01
Free call
Tell us your goals & timeframe, it only takes about 15 - 20 minutes.
02
We compare
We compare 60+ lenders and come back with the best 2–3 options.
03
You choose
You choose the lender that you prefer, including the rates & terms.
04
Ongoing support
We help after your settlement too, as loans always change over time.
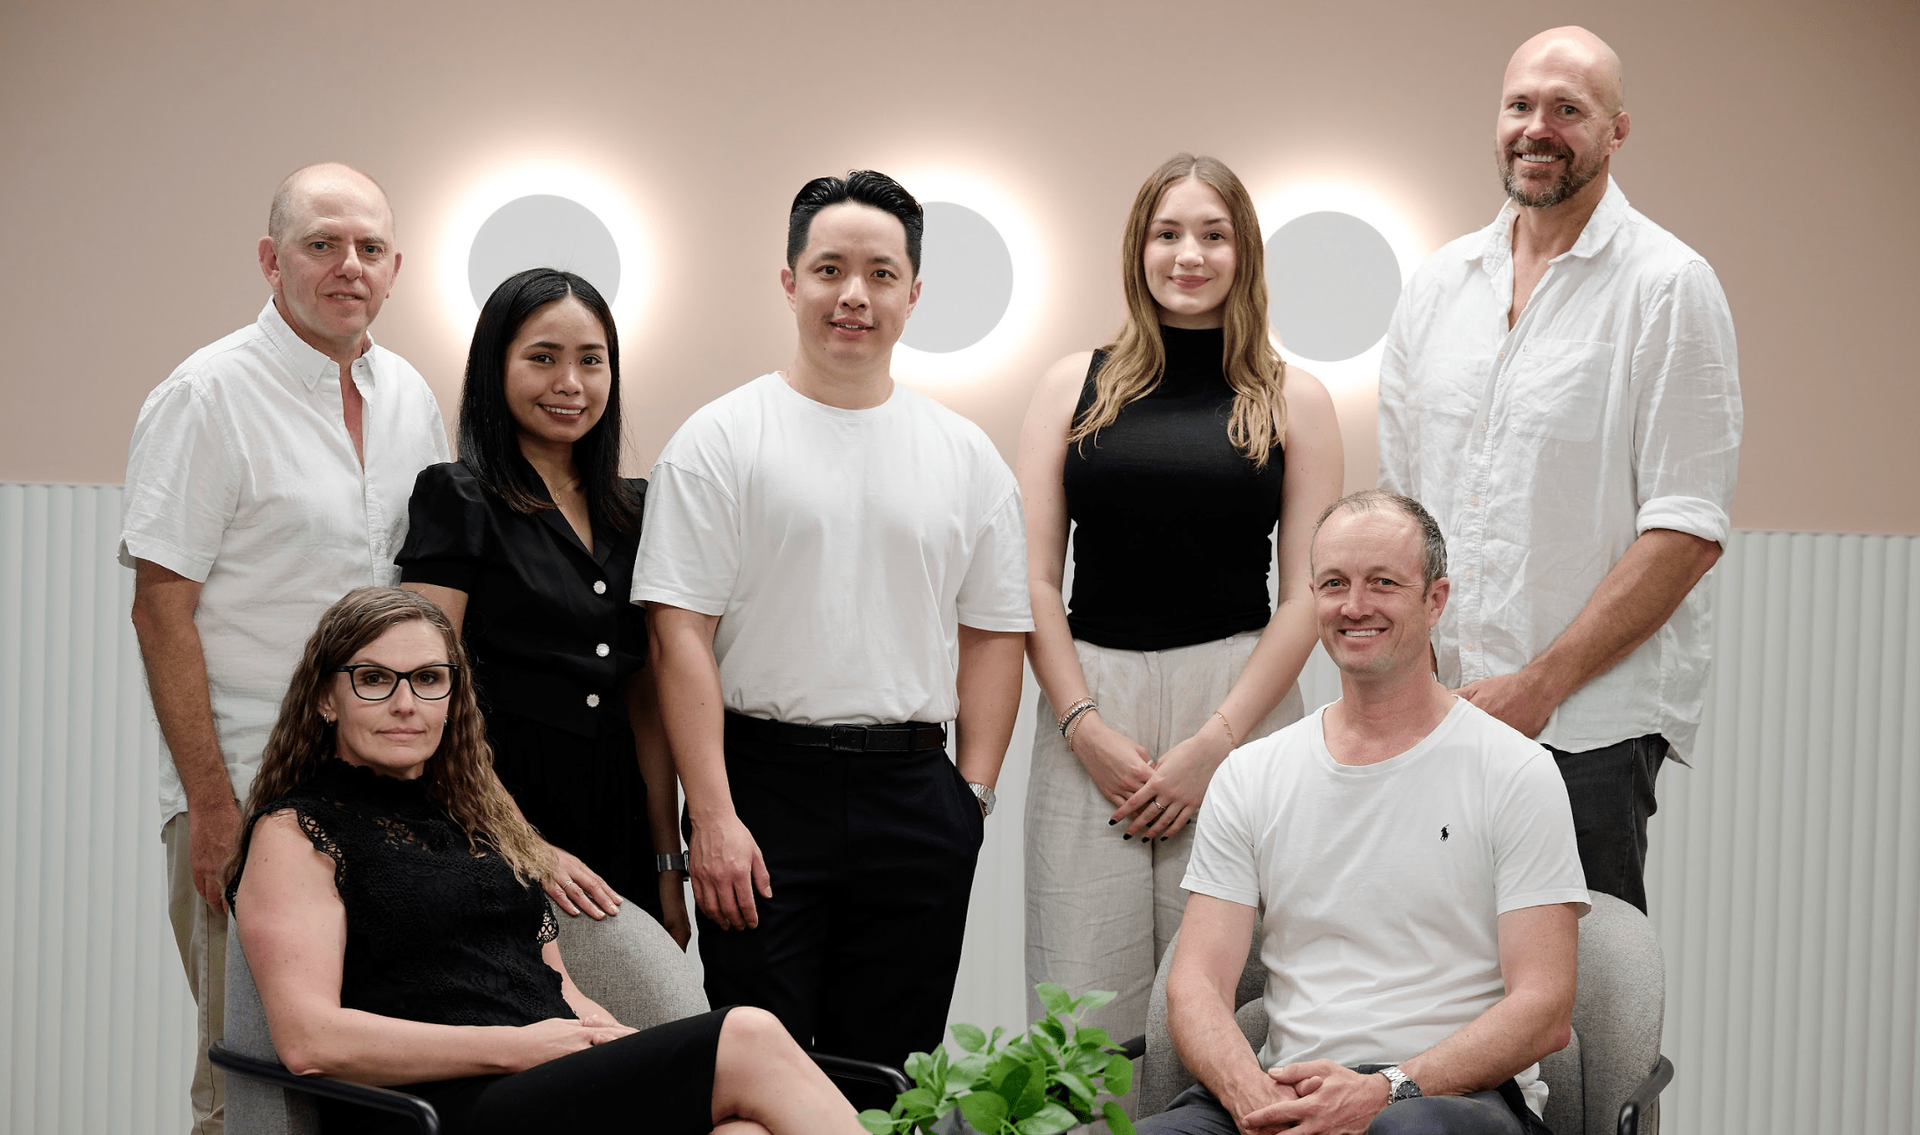
— our Frenchs Forest mortgage broker team
Like to see some more home loan options? Simply call or email us today.
Free chat, no obligations.
Damian Wallace
Director and Principal Broker
As the leader of our Mortgage Brokers Northern Beaches team, Damian is deeply committed to helping Frenchs Forest locals with the best possible lending outcomes, so they can live their best lives. Damian specialises in home and investment loans for our clients.
Justin Purll
Director & Senior Finance Specialist
Justin spent 20 years growing up on the Northern Beaches, studying accounting. However, Justin moved to Europe to pursue a professional rugby career. 14 years and two countries later, Justin returned to Australia, finding his new passion in mortgage broking.
— What our clients say
400+ Google reviews from real Frenchs Forest home owners.
Finding the right home loan can be daunting, even before the application process. That's why our Frenchs Forest Mortgage Broker experts get glowing reviews, we take care of everything.
— Some faqs we get asked
Frenchs Forest units have a $1,902,500 median - how much deposit is that compared with a house?
A 20% deposit at the unit median is $380,500, against $501,000 at the house median. CoreLogic's 2026 medians for Frenchs Forest are $1,902,500 for units and $2,505,000 for houses, a gap of $602,500.
The unit figure surprises people. Units in Frenchs Forest are mostly newer apartments, so the median reflects new stock. A deposit under 20% usually means lenders mortgage insurance (LMI), and LMI is rarely available on loans above about $2,000,000. On a median unit, the loan at 80% is $1,522,000, so there is some room for a buyer with a 10% deposit of $190,250 to find a lender. On a median house, the loan at 80% is already $2,004,000, so most house buyers need the full $501,000.
With newer apartments, lenders also look at the building itself, so we check a lender's view of the complex before you commit. Either way, transfer duty and legal costs come on top of the deposit, and they are a large sum at these prices.
I work at Northern Beaches Hospital - can I buy in Frenchs Forest with a 10% deposit and no LMI?
Possibly. Selected lenders waive LMI up to 90% of the property value for eligible professionals, and some go to 95% for medical practitioners. Whether you qualify depends on your occupation, your registration and each lender's own list, which differs from one lender to the next.
Here is what that means in Frenchs Forest, where the hospital is. CoreLogic's 2026 median house price is $2,505,000, so a 10% deposit is $250,500 and a 5% deposit is $125,250. The median unit price is $1,902,500, where 10% is $190,250 and 5% is $95,125. Waiver policies usually carry their own maximum loan size, so at these prices we confirm the limit with the lender before you rely on it.
Income is the other half. Shift penalties and overtime are treated differently by each lender. Some count all of it, some shade it, and some want a longer history first. For hospital staff with rostered income, choosing a lender that counts it fully can make a real difference to the outcome.
Why can't first home buyers use the 5% Deposit Scheme on a median-priced Frenchs Forest apartment?
Because the median is over the price cap. CoreLogic's 2026 median unit price for Frenchs Forest is $1,902,500, which is $402,500 above the $1,500,000 limit for the 5% Deposit Scheme (First Home Guarantee). The house median of $2,505,000 is $1,005,000 above it. Both are also over the $1,300,000 Help to Buy cap.
NSW transfer duty relief does not reach these prices either. The full exemption ends at $800,000 and the concession ends at $1,000,000, so a first home buyer at either Frenchs Forest median pays full duty.
So what do first home buyers do? Some buy with a larger deposit, often with family support: 20% at the unit median is $380,500. Some look for lower-priced stock within the suburb, though at the 2021 Census only 3.1% of Frenchs Forest dwellings were flats and 4.3% were semi-detached homes or townhouses, so choice is limited. Others start in a unit suburb and move later. The lowest unit median on the Northern Beaches is $960,000 in Dee Why (CoreLogic, 2026), which is under both caps.
Family households made up 86.3% of Frenchs Forest at the 2021 Census - what does that mean for my loan application?
It suggests many Frenchs Forest borrowers are established families upgrading, renovating or refinancing, and lenders assess those loans with close attention to household expenses. At the 2021 Census, 86.3% of Frenchs Forest households were family households and 61.2% of families were couples with children.
Ownership is high. The 2021 Census recorded 46.3% of homes owned with a mortgage and 36.8% owned outright, with 15.7% rented. The 2021 Census median weekly household income was $3,109, which should not be read as a current figure.
In practice, a few things follow. Dependent children raise the living expenses a lender allows for, so a family can usually borrow less than a couple on the same income. Many owners hold equity that can fund a renovation or the deposit on a larger home. And because rentals were a small share at the 2021 Census, investors are likely to be a minority here. If you are buying your first house, you may be competing with buyers who bring equity from a previous home.
Can a practice owner in the Frenchs Forest health precinct get a home loan and buy their rooms?
Both are possible, subject to lender approval, but each has different paperwork and a different deposit from a standard salaried home loan. Frenchs Forest is home to the Northern Beaches Hospital and its health precinct, so it is a natural question for practice owners.
For the home loan, self-employed borrowers need to prove income. Most lenders want two years of tax returns, and some accept one year or BAS statements. CoreLogic's 2026 median house price for Frenchs Forest is $2,505,000, where a 20% deposit is $501,000. Eligible professionals may qualify for an LMI waiver up to 90% of the property value at selected lenders, and up to 95% for medical practitioners at some.
Commercial property is assessed separately. Loans for consulting rooms or other commercial premises usually need a larger deposit than a home loan, and the lender looks at the lease and the business figures. The loans affect each other, because business debts count in your home loan assessment. As a mortgage broker we look at both together so one does not block the other.