— Mortgage Brokers Palm Beach
Home loan solutions, that are tailored to you.
WE COMPARE 60+ BANKS & LENDERS INCLUDING
— A simple process You'll love
More options are available, even if you're months away from buying or refinancing.
Many of our Palm Beach clients aren't ready to buy, they're planning, researching & weighing up options.
01
Free call
Tell us your goals & timeframe, it only takes about 15 - 20 minutes.
02
We compare
We compare 60+ lenders and come back with the best 2–3 options.
03
You choose
You choose the lender that you prefer, including the rates & terms.
04
Ongoing support
We help after your settlement too, as loans always change over time.
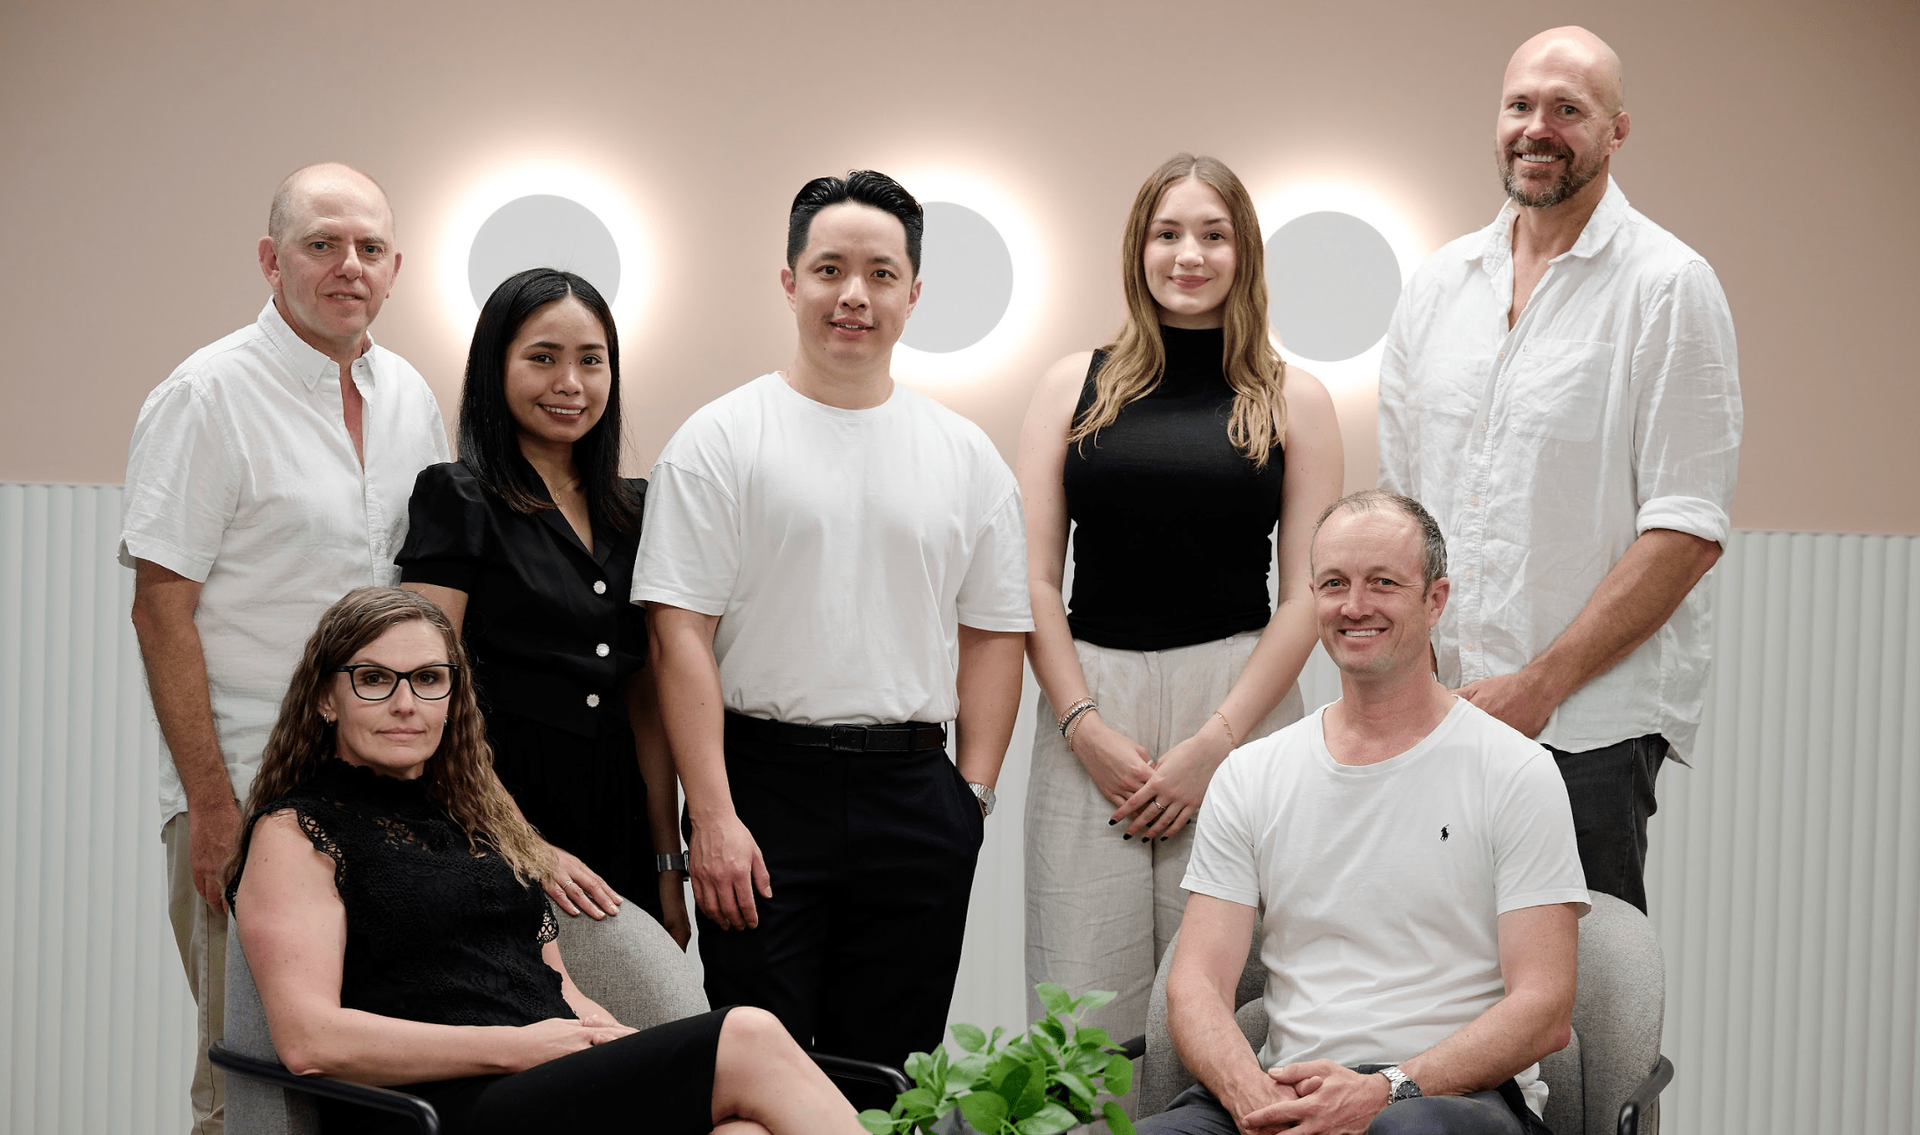
— our Palm Beach mortgage broker team
Like to see some more home loan options? Simply call or email us today.
Free chat, no obligations.
Damian Wallace
Director and Principal Broker
As the leader of our Mortgage Brokers Northern Beaches team, Damian is deeply committed to helping Palm Beach locals with the best possible lending outcomes, so they can live their best lives. Damian specialises in home and investment loans for our clients.
Justin Purll
Director & Senior Finance Specialist
Justin spent 20 years growing up on the Northern Beaches, studying accounting. However, Justin moved to Europe to pursue a professional rugby career. 14 years and two countries later, Justin returned to Australia, finding his new passion in mortgage broking.
— What our clients say
400+ Google reviews from real Palm Beach home owners.
Finding the right home loan can be daunting, even before the application process. That's why our Palm Beach Mortgage Broker experts get glowing reviews, we take care of everything.
— Some faqs we get asked
How much cash do I need up front for a Palm Beach house at the $5,360,000 median?
A 20% deposit of $1,072,000 is the realistic starting point for a Palm Beach house at the median. CoreLogic's 2026 median house price for Palm Beach is $5,360,000, and 20% down leaves a loan of $4,288,000. Transfer duty and legal costs are separate again, so the cash needed by settlement is higher than the deposit alone.
Smaller deposits exist on paper but rarely in practice at this price. A 10% deposit would be $536,000, yet a deposit under 20% usually means lenders mortgage insurance (LMI), and LMI is rarely available on loans above about $2,000,000. At prestige prices lenders often want deposits of 20% to 30%, so some buyers are asked for more than the 20% figure.
Palm Beach is also a prestige and holiday-home market with scarce comparable sales. That matters for your cash position, because a valuation can come in under the contract price and the buyer has to cover the difference. We suggest holding a buffer in reserve instead of committing every dollar to the deposit.
Will a lender write a $4,288,000 loan for a Palm Beach home?
Some lenders will, but a loan of $4,288,000 is assessed very differently from an everyday home loan. That figure is what remains after a 20% deposit of $1,072,000 on CoreLogic's 2026 median house price for Palm Beach of $5,360,000.
Loans of this size usually go to a credit assessor for manual review, not through automated scoring. The assessor looks closely at each income source, existing debts, other property and how the deposit was built. At prestige prices lenders often want deposits of 20% to 30%, and LMI is rarely available on loans above about $2,000,000, so there is little room to borrow a higher share of the price.
The valuation is the other moving part. Palm Beach has scarce comparable sales, so lenders can value conservatively. Each lender also sets its own maximum loan size. As a mortgage broker comparing more than 60 lenders, our team checks those limits before you make an offer, not after.
Why might a bank value a Palm Beach waterfront home below the price I agreed to pay?
A valuation can come in under the contract price in Palm Beach because the valuer has scarce comparable sales to rely on. Palm Beach sits at the northern tip of the peninsula and is a prestige and holiday-home market, so lenders can value conservatively. That caution tends to be stronger for waterfront and beachfront homes, where no two properties are alike.
When it happens, the lender bases the loan on its own valuation and the buyer has to cover the difference. Against CoreLogic's 2026 median house price for Palm Beach of $5,360,000, even a modest shortfall is a large sum of cash.
There are practical steps you can take. Choose a lender whose valuers know the upper peninsula. Keep some funds in reserve above your deposit. Ask for an insurance quote early, because a lender needs the home insured before settlement and cover for a property close to the water can take longer to arrange. Where a first valuation looks light, we can ask a second lender to value the property.
With 55.3% of Palm Beach homes owned outright at the 2021 Census, how do downsizers here fund their next purchase?
Downsizers in Palm Beach who own outright can usually fund the next home from the sale of the current one, so the main question is often timing, not borrowing power. At the 2021 Census, 55.3% of Palm Beach homes were owned outright and the median age was 58, which suggests many owners who sell will be selling a home with no loan against it.
If you sell first, you know exactly what you have to spend, but you may need somewhere to live in between. If you buy first, a bridging loan can cover the gap. The lender takes both properties as security, interest is usually added to the loan until the old home sells, and lenders commonly allow up to 6 months to sell an existing home.
Borrowing close to retirement is possible, though lenders want an exit strategy for any loan that runs past retirement age. With CoreLogic's 2026 median house price for Palm Beach at $5,360,000 and scarce comparable sales, we suggest not relying on a quick sale at a set price.
Palm Beach had a median age of 58 at the 2021 Census - what kind of lending is common there?
Lending in Palm Beach is often about equity, not first purchases, because the 2021 Census shows far more homes owned outright than owned with a mortgage. At the 2021 Census, 55.3% of Palm Beach homes were owned outright, 23.3% were owned with a mortgage and 16.5% were rented, and the median age was 58.
Those figures point to long-term owners, downsizers and buyers who bring equity from another property. Couples without children made up 58.2% of Palm Beach families at the 2021 Census. The 2021 Census also recorded a median monthly mortgage repayment of $4,000, a figure that is now several years old and should not be read as a current cost.
For a borrower, this shapes the conversation with a lender. Typical requests in a suburb like this are releasing equity from a home with no debt, funding a second property, or borrowing for a holiday home that is not the main residence. Lenders treat each of those differently, so it helps to be clear about how the property will be used before an application goes in.